What Is a Supply Deficit in Metals? A Guide (2026)
A supply deficit in metals occurs when the quantity of a metal consumed in a year is greater than the quantity supplied by mining and recycling over that same year. The shortfall has to be covered by drawing down metal that was already produced — and that gap between the annual flow of supply and the annual flow of demand is what analysts call a market deficit.
It is a flow measure, not a countdown. A deficit tells you that buyers took more metal out of the market than the industry put in. It does not mean the metal ran out, and on its own it does not tell you what the price did next.
The formula, in plain terms: total consumption minus mine production minus net recycling supply equals the supply deficit for that period.
Read that as a market balance sheet. Everything the world buys in a year — fabricated metal for industry, jewellery, electronics, plus investment bar and coin buying and central bank purchases — sits on one side. Everything mined and recycled sits on the other. When the demand side is bigger, the difference has to come from somewhere, and that somewhere is inventory.
What Is a Supply Deficit in Metals?
Define it once more plainly: a supply deficit is the quantity of metal the market consumed above the quantity it produced, during a specific reporting period, measured in tonnes or million troy ounces. Analysts almost always add a second figure — the deficit as a percentage of total demand — because a 20 million ounce number means very different things in silver and in platinum.
Two kinds of deficit get described with the same word, and the distinction matters more than anything else on this page. A cyclical deficit is a one-year event, usually triggered by a strike, a flood, a smelter outage or a smelter maintenance cycle. A structural deficit is the same imbalance repeating year after year because the supply side is physically unable to expand in time.
| Feature | Cyclical deficit | Structural deficit |
|---|---|---|
| Typical duration | Months, or a single year | Three years or more, often several consecutive |
| Main cause | Disruption — strike, weather, outage, maintenance backlog | Declining ore grades, permitting delays, depleted mines, capital discipline |
| Can supply respond to a higher price? | Usually yes, within a year or two | No — new mines take roughly seven to 15 years from discovery to first production |
| How it ends | Restarted production, recovered output | Demand destruction, substitution, or a sustained recycling response |
| Effect on price | Often brief and sharp, sometimes barely visible | Persistent scarcity premium, but still gated by macro and investment demand |
| Worked example | A smelter maintenance cycle cuts refined platinum output for two quarters | Silver, where most output is a by-product of lead, copper and zinc mining |
One more term trips people up. A deficit is not the same thing as a market balance going negative in a formal sense — it is simply the market balance expressed as a signed number, where the convention is usually to report the shortfall as a positive number and a surplus as a negative one. Check which convention a publisher uses before comparing two charts.
How Is a Metal Supply Deficit Calculated?
The calculation is subtraction. Take total consumption for the year, subtract mine production, subtract the net contribution of recycled material, and whatever is left is the deficit. Here is an illustrative example using round numbers so the mechanics are obvious — these are not real market figures.
Illustrative silver market, one year: total consumption of 500 million ounces, of which 300 million is industrial and fabrication, 190 million is jewellery and silverware, and 10 million is net physical investment. Mine supply delivers 420 million ounces. Recycling adds 30 million ounces. Total supply is 450 million ounces, so the deficit is 500 minus 450, or 50 million ounces — which is 10% of total demand.
Run the same year as a surplus and the sign flips. If consumption falls to 430 million ounces against unchanged supply of 450 million, the market is in a 20 million ounce surplus, and the 10% deficit becomes a surplus of about 4.7% of demand. Same mines, same recycling network, opposite conclusion, entirely because of the demand line.
| Component | Deficit year (Moz) | Surplus year (Moz) |
|---|---|---|
| Industrial and fabrication demand | 300 | 250 |
| Jewellery and silverware demand | 190 | 170 |
| Net physical investment | 10 | 10 |
| Total consumption | 500 | 430 |
| Mine production | 420 | 420 |
| Recycled supply | 30 | 30 |
| Total supply | 450 | 450 |
| Balance | 50 deficit | 20 surplus |
| Deficit as % of demand | 10.0% | 4.7% surplus |
Real published numbers come with more components and more uncertainty, but the arithmetic is the same. Precious metals analysts split demand into fabrication, jewellery, silverware, photography (historically for silver, now largely gone), physical investment and, for gold, central bank buying. Supply gets split into mine production, net recycling and, for some markets, producer hedging or net official sector sales.
Base metals are measured in tonnes or thousand tonnes rather than ounces, and the demand categories are different again: refined consumption for construction, power grids, transport, machinery and, increasingly, data centre and grid buildout. The International Copper Study Group publishes refined production and usage figures on a monthly basis, which is why copper analysts talk about a market balance in kilotonnes.
Always convert the deficit to a percentage of demand before drawing conclusions. A 5 million tonne copper gap sounds enormous until you compare it with total global refined usage of roughly 27 million tonnes, at which point it reads as under 20% of annual demand and explains itself within a single quarter of demand destruction.
What Counts as Available Metal Supply?
Four things count, and readers routinely mix them up.
Primary supply is mine production — the metal pulled out of the ground in the reporting period. For most base metals this is the dominant term. For silver it is unusually complicated, because the majority of silver ounces are recovered as a by-product of mining lead, copper and zinc rather than from dedicated silver mines.
Secondary supply is recycled metal: scrap jewellery, industrial scrap, and end-of-life product recovered and refined. Recycling is the one supply source that responds quickly to price. When prices rise, more scrap surfaces, and it shows up within months.
Above-ground inventories are the metal already in existence — in exchange vaults, in bonded warehouses, in refiner and trader holdings, in manufacturer stocks, and in the hands of private holders. This is a stock measured in millions of ounces, not a flow. It is the buffer that absorbs a deficit without any price response at all, and how many months of demand cover remain is the single most useful number for judging how urgent a deficit really is.
Net trade flows round it out. Imports and exports move metal between regions rather than adding to the global total, so a regional deficit can coexist with a global surplus — which is exactly what happens in the gold market, where western demand repeatedly drains metal that sits in vaults elsewhere.
What Causes Supply Deficits in Metals?
Eight things come up again and again. The first six act on the supply side; the last two describe the demand side of the same equation.
- Declining ore grades. As a mine works through its easiest material, the same tonne of rock yields less metal, so costs rise and output falls at constant tonnage. This is a permanent, geological pressure rather than a shock.
- Mine depletion and aging assets. Producing mines are finite. Once a body is exhausted, the resource has to be replaced, and replacement rarely matches the output that left.
- Permitting and community constraints. Exploration licences, environmental reviews and local opposition can add years between discovery and production, and juniors with thin balance sheets frequently cannot fund the wait.
- Capital discipline and underinvestment in exploration. When prices fall, exploration budgets are cut first. Fewer discoveries today means less supply in ten years, which is why drilling budgets are a leading indicator of supply a decade out rather than next quarter.
- Geopolitical and operational disruption. Export restrictions, sanctions, power grid failures, flooding, strikes and smelter maintenance backlogs all remove supply on a schedule nobody controls.
- By-product inelasticity. When most of a metal’s supply comes out of another metal’s mine, a price signal for the by-product does almost nothing. Silver is the classic case: a high silver price does not make miners dig more silver mines, because the decision is made on the economics of lead, copper and zinc.
- Demand running ahead of forecasts. Fabrication demand can grow faster than modelled, and each new demand category — solar, grid buildout, EV, electronics, data centres — adds to the total without any warning.
- Weaker secondary supply. Recycling volumes are partly a function of how much product was sold years ago and how readily owners release it. Anything that delays that release tightens the balance.
Geographic concentration multiplies the effect of any one of these. South Africa historically accounted for the large majority of platinum mine supply, and the copper concentrate market turns on a handful of producing countries. When one region hits a power problem, the global balance shifts.
How Does a Supply Deficit Affect Metal Prices?
Usually upward, eventually, and by less reliably than the headline suggests. A deficit removes metal from inventory without replacing it, so the buffer that normally caps price moves thins out. If demand holds, that thinning eventually forces a higher price. That is the whole mechanism.
The catch is timing. Metal prices are set every second by expectations, currency moves and the positioning of large futures participants — not by tonnage. A deficit can be announced, confirmed and repeated for several years while price does very little, because the market is absorbing it out of above-ground stocks. The World Platinum Investment Council has published estimates putting above-ground platinum stocks at roughly five months of demand cover, which is a buffer, not an emergency, but it is also not infinite.
Mine development lead times are the other constraint. Discovering a deposit, securing permits, financing construction and commissioning a plant runs roughly seven to 15 years. So a deficit cannot be fixed by price within any reasonable horizon, which is precisely why a structural deficit is a real phenomenon rather than a self-correcting one.
Deficits resolve in four ways, and only the first is quick: demand destruction, where buyers use less or a cheaper substitute; substitution, where a different material takes the load; a recycling surge as higher prices pull scrap out; and eventually new mine supply arriving years late. Copper analysts watch treatment and refining charges for the same reason — these are the fees smelters charge to process concentrate, and when they fall to or below zero, it means smelters cannot get enough concentrate. It is the closest thing the copper market has to a real-time shortage gauge, and it updates monthly through ICSG and exchange data.
Is a Supply Deficit in Metals the Same as a Shortage?
No, and this is the most common mix-up in metals commentary. A deficit is a flow: annual consumption exceeded annual supply by some amount. A shortage is a stock condition: there is not enough metal available to satisfy orders at the current price, and buyers are rationed.
That is why someone can be in a multi-year deficit and still walk into a dealer and buy any quantity of metal they want. The dealer is drawing on deep above-ground stocks and exchange availability, not on this year’s mine output. The metal exists. The question is only how fast the buffer is being spent.
A shortage, by contrast, shows up operationally: fabricators bidding up premiums, delivery times extending, buyers substituting, and a shortage premium appearing on top of the quoted price. A deficit is a bookkeeping fact; a shortage is a market condition.
What Should Investors Look For?
When you read that a metal is in deficit, run through this list before drawing any conclusion.
- Check the unit and the date. A deficit quoted in ounces without a year attached is useless, and this data changes monthly. Every figure should carry a unit, an as-of date and a named publishing body.
- Convert to a percentage of demand. This is the only way to compare a precious metal deficit with a base metal deficit, or this year’s gap with last year’s.
- Watch inventory, not just the balance. Exchange stocks, warehouse holdings and reported months of demand cover tell you whether the deficit is being absorbed quietly or is starting to bite.
- Count consecutive years. One deficit year is an event. Four in a row is a trend, and the trend is what separates a structural from a cyclical imbalance.
- Track treatment and refining charges for copper. A persistent slide toward zero, or below, tells you smelters are competing for scarce concentrate — a physical signal that shows up long before refined balances are revised.
- Check the supply pipeline. Committed projects, new mine announcements, permitting timelines and exploration budgets tell you whether the supply side is capable of responding at all.
- Look at what demand is doing. Industrial demand, investment demand and central bank buying all count, and investment flows can swamp a small deficit in a small market.
- Know who is publishing. The Silver Institute and the Metals Focus World Silver Survey cover silver; the World Platinum Investment Council covers platinum; ICSG covers copper; USGS Mineral Commodity Summaries give the broadest annual cross-metal view; the International Energy Agency’s Global Critical Minerals Outlook frames the energy transition demand side. Industry bodies are reliable but not neutral, so corroborate across two of them.
Be sceptical of any deficit claim that arrives without a source, a date or a percentage of demand. That combination of missing detail is common in promotional material rather than analysis.
Examples of How a Metal Supply Deficit Can Develop
Silver, a by-product structural deficit. The Silver Institute has projected that 2026 marks a sixth consecutive year of deficit, estimating the shortfall at roughly 46 to 47 million ounces. The mechanism is the one described above: most silver is recovered from lead, copper and zinc operations, so a higher silver price does not pull new supply into the market on any useful timescale. Whether that converts into price depends heavily on investment demand, which is far more price-sensitive than industrial demand and far more capable of moving the price on its own.
Platinum, a deficit with a measured buffer. Platinum has run with persistent deficits alongside falling mine output and, per the World Platinum Investment Council, above-ground stocks of roughly five months of demand cover. Here the deficit story is doing something specific: it is gradually consuming the buffer that would otherwise absorb a shortfall, and shrinking the cushion. The public case for platinum has leaned heavily on this dynamic, and the honest case says the same thing more quietly — inventory is finite and the drawdown is real, but the price response still depends on the macro environment.
Copper, the forecast structural gap. Several years back, executives from Canadian miners including Hudbay and Iamgold told mining.com that any credible prognosis pointed to a copper structural deficit of five to seven million tonnes starting within three or four years. That is a forecast, not a settled fact, and forecasts age badly. What has proved more durable is the mechanism: treatment and refining charges sliding toward zero as smelters compete for concentrate.
The energy transition metals, still a work in progress. Lithium and nickel have moved in and out of deficit repeatedly as EV demand estimates swung and new capacity arrived. That whipsaw is a useful contrast with silver: where the constraint is genuinely physical and geological, deficits persist; where the constraint is a forecast of future demand, deficits appear and disappear as the forecast is revised.
| Metal | Most recent published balance | Consecutive deficit years | Publishing body |
|---|---|---|---|
| Silver | Projected deficit of about 46-47 million ounces for 2026 | Sixth consecutive year | The Silver Institute |
| Platinum | Persistent deficit alongside above-ground stocks of roughly five months of demand cover | Multi-year | World Platinum Investment Council |
| Copper | Refined balance published monthly in tonnes; a structural gap of five to seven million tonnes has been forecast for the coming years | Forecast rather than confirmed | International Copper Study Group |
| Copper concentrate | Treatment and refining charges at or below zero, signalling concentrate scarcity | Ongoing | Exchange and smelter data |
| All metals | Annual mine production and reserves context | Not applicable | USGS Mineral Commodity Summaries |
| Energy transition metals | Demand-side outlook to mid-century | Varies by metal | International Energy Agency |
As of October 2026. Published balances are revised after the fact, so treat these as current estimates rather than settled history.
Common Misunderstandings About Metal Deficits
A deficit does not guarantee an immediate price rise. This is the big one. The balance is a physical fact and the price is a financial one, and a lot of other variables sit between them — rates, currency, risk appetite, and investment flows into and out of the metal. A deficit tells you the physical market is tightening. It does not tell you when, or by how much, that tightening reaches the quoted price.
A deficit does not mean the metal is unavailable. It is a flow imbalance, not an empty shelf. Deep above-ground stocks mean you can buy what you want today, and that is exactly how the market absorbs deficits for years at a time.
One mine closure does not decide the market. A single disruption matters when inventories are already thin and the metal is concentrated in one region. In a well-supplied market with large stocks, the same closure is a rounding error.
A high price does not bring new supply quickly. The seven-to-15-year mine development timeline is the reason deficits can persist. If supply responded to price within a year, structural deficits would not exist.
Headline deficit figures are not directly comparable. Six million ounces of silver, six million tonnes of copper and six million ounces of platinum are entirely different statements about tightness. Always reduce to a percentage of demand.
A deficit is not the same as a bull case. It is one input among several, and it is the input most easily overstated by parties with a commercial interest in the metal.
Frequently Asked Questions
A supply deficit in metals means the quantity of a metal consumed over a period is greater than the quantity supplied by mining and recycling over the same period. The difference has to be drawn from existing above-ground inventories. Analysts calculate it as total consumption minus mine production minus net recycled supply, then express the result in tonnes or million troy ounces and as a percentage of total demand.
The Silver Institute has projected a silver deficit of roughly 46 to 47 million ounces for 2026, which would be the sixth consecutive year of shortfall. Silver supply is largely a by-product of lead, copper and zinc mining, so a higher silver price does not quickly pull new supply into the market. The gap is measured against total consumption of roughly 1.2 billion ounces including industrial, jewellery and investment demand.
A deficit and a shortage are different things. The silver deficit is a flow measure: annual consumption exceeded annual supply by some amount. A shortage is a stock condition in which buyers are rationed and cannot obtain metal at prevailing terms. Because above-ground silver stocks remain substantial, physical buyers can still purchase any quantity they want today. The deficit is being absorbed by drawing down those stocks rather than by an absence of metal.
A deficit supports higher prices over time but does not guarantee an immediate move, and the mechanism is indirect. The deficit draws down above-ground inventories, and once the buffer becomes thin enough, buyers bid metal up to conserve what remains. Until then, price is set by expectations, currency moves and investment flows rather than tonnage. That is why a published deficit can run for several years with a muted price response before it becomes material.
A cyclical deficit caused by a strike, flood or smelter outage usually resolves within a year or two as production resumes. A structural deficit can persist for many years, sometimes indefinitely, because the supply side cannot respond in time. New mines typically take roughly seven to 15 years from discovery to first production, and much silver supply is a by-product of other metals that cannot be increased on a silver price signal alone.
Several named bodies publish usable figures. The Silver Institute and the Metals Focus World Silver Survey cover silver, the World Platinum Investment Council covers platinum, the International Copper Study Group publishes monthly refined copper balances, the USGS Mineral Commodity Summaries give an annual cross-metal view of mine production, and the International Energy Agency frames energy transition demand. Industry bodies are consistent but not neutral, so corroborate any figure across two sources.
Conclusion: Start With the Supply-Demand Balance
A supply deficit in metals is a simple thing stated precisely: annual consumption exceeded annual mine production plus recycled supply, and the difference came out of inventory. Everything else follows from that one balance, including why the metal may still be easy to buy, why a deficit can persist for years, and why it does not by itself settle where the price goes.
Before acting on any deficit claim, check four things: the unit, the as-of date, the deficit as a percentage of total demand, and the publishing body behind it. Then look at inventories. That is where the real signal lives.
Source: https://www.pgm-blog.com/what-is-a-supply-deficit-in-metals/
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
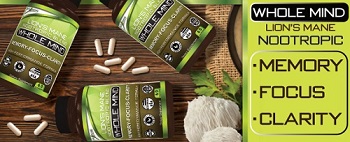
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,834,037,191 |
| Stories: | 8,715,887 |
Whistler Blowers, Insiders

