What Are Export Restrictions on Critical Minerals? (2026)
Export restrictions on critical minerals are government-imposed limits on shipping strategic minerals and their processed forms out of a producing country. They range from outright bans to quotas, export licences, taxes and domestic processing mandates, and they are usually aimed at securing supply for national industries or gaining leverage in trade disputes.
Most readers arrive at this topic after a headline about China, rare earths or a sudden move in a battery metal price. The policy language in those stories gets compressed into noise, and the difference between a ban and a licence requirement gets lost. That distinction matters, because one closes a market and the other rations it.
The guide below breaks the topic into the pieces an investor actually needs: what counts as a restriction, which minerals sit inside each processing stage, who is using which instrument, and how to tell a durable supply change from a headline that fades. Policy details move quickly, so treat every example as a framework to check against current official notices rather than a fixed list.
What Are Export Restrictions on Critical Minerals?
An export restriction is a rule that limits or conditions the shipment of a specific good out of a country. Applied to critical minerals, it targets materials governments see as strategically important, such as rare earths, gallium, germanium, antimony, tungsten, graphite and processed battery components.
It helps to separate the term from three neighbours people often confuse it with. An export restriction governs outbound goods. A tariff taxes them. A mining ban stops extraction inside the country, and an exploration limit stops new project work. Only the first group touches what leaves the border.
Critical minerals themselves are defined by supply risk rather than by scarcity. The US Geological Survey lists minerals whose supply chains are import-dependent, concentrated in a handful of countries, or lacking viable substitutes. A mineral can be geologically common and still be on the list because the processing happens in one place.
Why Countries Impose Critical Mineral Export Controls
The stated reasons and the actual reasons rarely match exactly, and investors who only read the stated ones get caught out. Here are the motivations that show up most often.
- National security. Materials used in munitions, radar, semiconductors and magnets sit inside defence procurement rules, so governments treat them differently from ordinary commodities.
- Supply-chain leverage in a trade dispute. Restrictions create a negotiating lever that can be applied quickly and withdrawn quietly.
- Forcing domestic processing. A common policy is to restrict raw material exports while allowing refined or fabricated exports, so value-added stays onshore.
- Building domestic industry. Batteries, magnets and semiconductor components are targeted for local production, and export controls protect the young domestic firms from cheaper imports.
- Resource conservation and environmental goals. Water use, tailings and energy intensity give regulators a justification for slowing depletion.
- Market stabilisation. Where a miner dominates a small market, controlling the export pace can blunt a price collapse.
The transmission runs through the supply chain, not the mine. Restricting the export of processed graphite from a producing country does not remove graphite from the earth; it removes the anode material that battery assemblers in other countries had already planned around. If qualification of a replacement material takes nine months, a six-month licence freeze bites well before any new supply appears.
Semiconductors work the same way. Gallium and germanium are minor inputs by volume, but they are hard to substitute inside compound semiconductors, fibre-optic components and power electronics. A restriction there is measured in fab delays rather than in dollars of ore.
Which Minerals and Processed Materials Are Affected?
The single most useful thing a reader can learn is that a mineral name on a headline rarely tells you what is actually restricted. Controls are written against a processing stage and a tariff code, and the stages behave very differently in a supply chain.
| Stage | What it is | Why control bites here | Examples |
|---|---|---|---|
| Ore | Unprocessed material straight from the mine | Low value density, easy to substitute at source | Iron ore, bauxite, tantalum concentrate |
| Concentrate | Partially upgraded material, often still a bulk commodity | Where beneficiation bans usually bite | Nickel ore, bauxite, graphite flake concentrate |
| Refined metal or compound | High-purity chemical form used in manufacturing | Hardest stage to replicate quickly | Lithium carbonate, cobalt sulphate, high-purity graphite |
| Permanent magnet or component | Fabricated input assembled from refined material | Direct substitute for manufacturers | Neodymium-iron-boron magnets, samarium-cobalt magnets |
| Minor metals and metalloids | Small-volume inputs to electronics and optics | Supply is geographically concentrated in a handful of refineries | Gallium, germanium, antimony, tungsten, tellurium, bismuth, indium |
| Finished assemblies | Batteries, cells, modules, devices | Where component-level controls become product-level controls | Lithium-ion batteries and battery components |
Within those stages, treatment varies by jurisdiction and by policy status. Some minerals are banned outright to specific destinations. Others require a government licence that is granted case by case. A third group has no restriction at all but sits on a watch list, which is why reading a critical minerals list as a ban list produces the wrong conclusion.
What Are Export Restrictions on Critical Minerals Used For?
Each instrument does something different, and the difference shows up in how quickly supply responds.
- Export ban. Shipments stop. Fastest impact on price, hardest to reverse politically, and the instrument most likely to trigger a trade dispute.
- Quota. A fixed volume or value is allowed for a period. Supply is capped but predictable, so buyers can plan around the ceiling.
- Licensing. Every shipment needs approval from a ministry. This is the most common instrument in practice, and it is more flexible than a ban because approvals can be granted, delayed or refused.
- Export tax or royalty. The mineral still moves, but the state captures part of the value. Used most often to raise revenue or discourage depletion.
- Domestic processing requirement. Raw exports are restricted while refined exports are permitted, which pushes foreign buyers toward local refineries and local partners.
- End-user and end-use review. Permits depend on who is buying and what they intend to make. This is where dual-use language does its work.
- Anti-transshipment rules. Controls on goods made abroad that contain a small amount of controlled Chinese-origin content, which closes a common routing workaround.
- Entity listing. Named companies are blocked regardless of the product. This is targeted rather than systemic, and it rarely changes total supply.
A licensing system is worth understanding separately from a ban because it converts a policy into a queue. If approvals flow, volumes keep moving and prices settle. If approvals stall, the effect converges on a ban without the legal drama. That is exactly the distinction retail traders in mining equities argue about, and it is why the same announcement can produce opposite price reactions on different days.
How Export Controls Are Enforced
Enforcement happens at the border, and it follows a fairly repeatable sequence.
- Classification. The shipment is matched to a tariff code and to the controlled goods catalogue. Controls are written against codes, so a product that sits just outside the code escapes the rule.
- Licence application. The exporter applies to the ministry or export control office. In China’s case that is the Ministry of Commerce, which publishes announcements numbering each change.
- Documentation. The applicant supplies end-user details, intended use, and the contract terms of the buyer.
- Review. Officials check the end user, the end use and sometimes the downstream customer. Defence and dual-use applications get the closest attention.
- Customs validation. Customs codes and certificates are checked against the licence at the point of export.
- Destination checks. Authorities may confirm that the importing country matches the declared end use, which is how diversion is detected.
Enforcement is rarely uniform across processing stages. A refined product may face one rule while its concentrate faces none, and the same mineral can be open to one destination and closed to another. Rules also move faster than most compliance systems can follow, so a company that checked the catalogue last quarter may be out of date today.
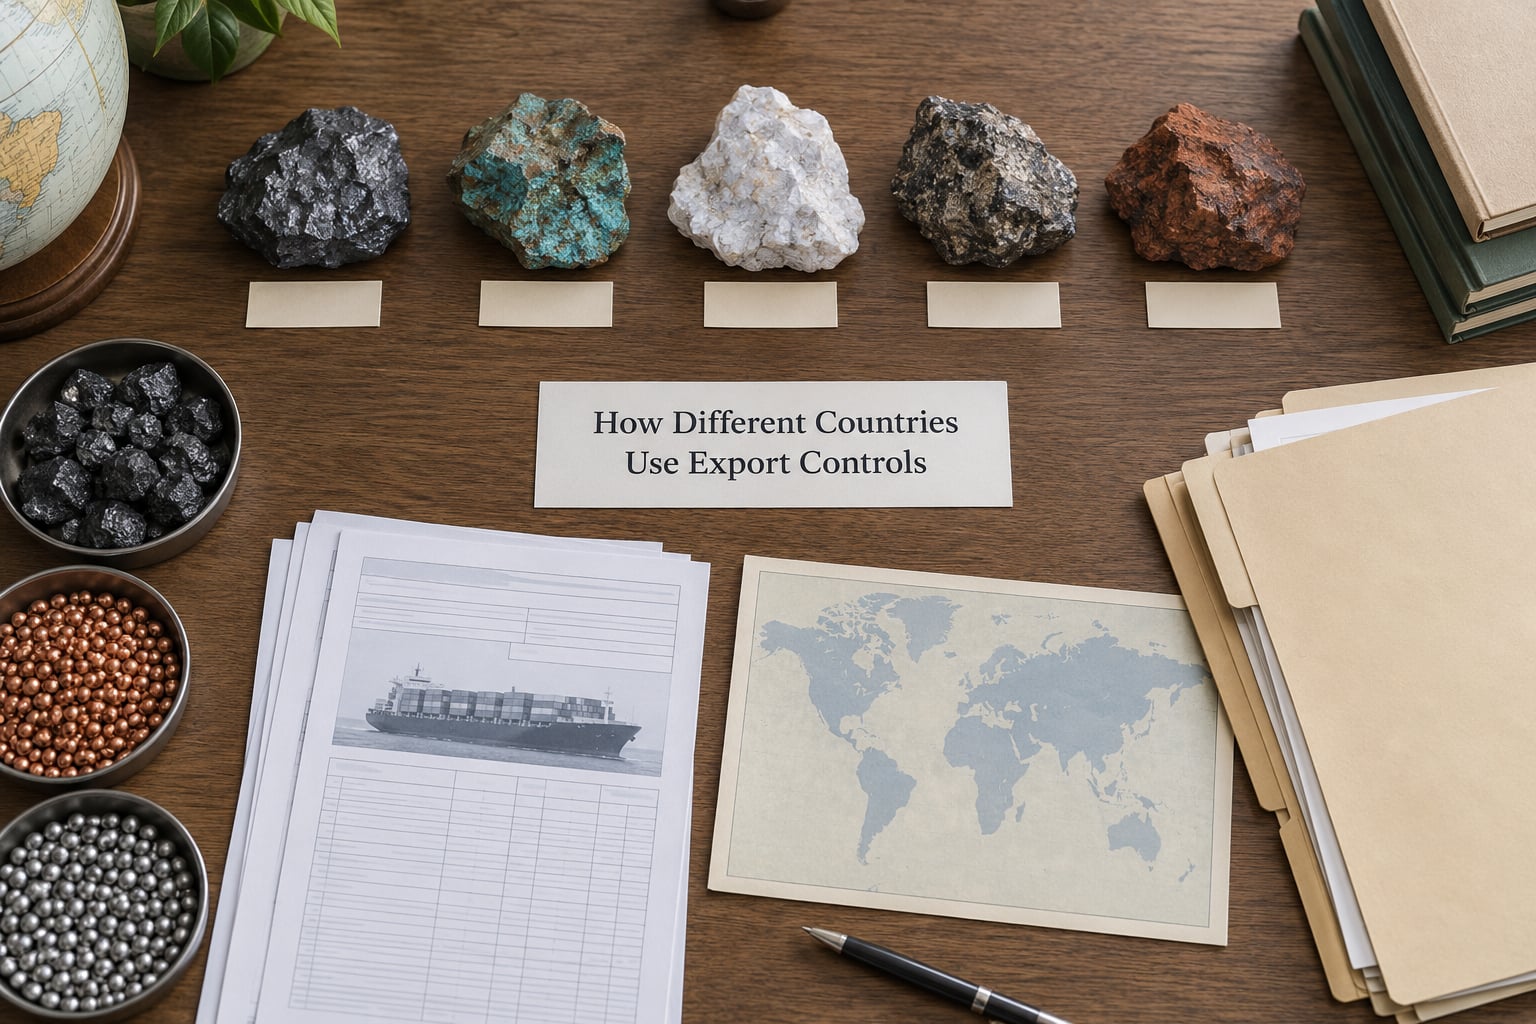
How Different Countries Use Export Controls
No two jurisdictions run the same system, and treating them as one story is the most common analytical error.
China is the dominant user of material export controls. Through the Ministry of Commerce and its dual-use catalogue, it has moved from licence requirements on graphite and rare-earth magnet technology in 2023 to broader measures: controls on battery-related items, medium and heavy rare earths and superhard materials announced in November 2025, plus foreign re-export licensing and technology controls in October 2025. Several minerals have also been restricted for specific destinations rather than universally.
That October 2025 re-export rule is the one that catches people out. It treats goods manufactured outside China as controlled when controlled Chinese-origin content exceeds 0.1% of the value. A manufacturer in another country can end up needing a Chinese licence for a product it never shipped to China, which extends the reach of the system well beyond Chinese exports.
The United States runs its controls in the opposite direction. Rather than limiting mineral exports, it restricts advanced technology and semiconductor equipment leaving the country, and it uses tariffs, Section 232 investigations and the Defense Production Act to build domestic and allied supply. It has also maintained a critical minerals list and strategic reserves, and the two systems form a two-way ratchet: one restricts materials out of the East, the other restricts technology out of the West.
The European Union uses the Critical Raw Materials Act to set extraction, processing and recycling targets and a single list of strategic raw materials. Its chosen instrument is diversification rather than restriction, which tells you something about where the EU sees its leverage.
India treats critical minerals as an industrial policy question, with the National Critical Minerals Mission and state-run exploration agencies aimed at securing overseas assets and domestic processing.
Indonesia has used a domestic processing requirement on nickel ore, forcing foreign smelters to build inside the country. The Democratic Republic of the Congo has moved cobalt toward export restrictions and quota management. Zambia and Namibia have considered or imposed limits on raw concentrate exports in copper and uranium supply chains. These are all beneficiation strategies dressed in different language, and they all have the same core effect: the raw material stays, the refining margin follows.
Why Export Restrictions Change Commodity Prices and Supply Chains
The path from policy to price runs through availability. Restricting supply tightens the market at the margin, which shows up first as a regional premium rather than a change in the global benchmark. Buyers who cannot get the material nearby pay more for freight and expedite, and that cost lands in the delivered price of the finished component.
Substitution is the second channel, and it is slower than headlines suggest. Swapping a magnet grade or a battery anode takes qualification time, and the qualification has to happen at the buyer. That means the first price reaction can be sharp and the second can fade, when buyers discover they had more inventory or an approved alternative than they thought.
Over a longer horizon the effect changes shape. High prices pull forward new mine development, recycling economics improve, and buyers redesign products to use less of the constrained material. At that point the restriction stops driving price and starts driving project economics instead.
Stockpiles and alternative producers moderate the shock. Where a strategic reserve exists, buyers can bridge a few months rather than bid up the market. Where another country can scale supply within a year, the restriction creates a premium rather than a shortage. The same policy produces very different market outcomes depending on which of those two conditions hold.
The 2010 rare earth cutoff to Japan is the cleanest historical example. A maritime dispute triggered an informal halt in shipments, and prices moved sharply within weeks. When the flow resumed, much of the price move reversed, which is the pattern traders still expect today from announcement-driven spikes.
What Export Restrictions Mean for Mining and Materials Companies
For producers and refiners, a control changes the terms of the business rather than just the price.
- Permitted volume becomes the constraint. A licence ceiling matters more than a spot price when it caps what a producer can physically ship.
- Domestic processing access is the strategic asset. Producers with refining capacity inside the restricted jurisdiction hold a structural advantage over those shipping concentrate out.
- Government bargaining power rises. When a state can approve or refuse each shipment, it gains a direct lever over contract terms and investment decisions.
- Project economics shift. Domestic processing mandates change the capital required, the timeline and the returns on a project, usually by adding refining cost that has to be earned back.
- Compliance cost rises. Classification, end-user documentation and customs handling are now a recurring operating expense rather than an occasional one.
- Diversified mine bases carry a premium. Assets in several jurisdictions are worth more when any one of them can close.
Processors face the opposite exposure. A company whose only route to customers runs through a licensing regime inherits the policy risk without owning the mineral. That is why refiners outside the restricting jurisdiction have been the most exposed part of the chain during the last few years, and why new refining capacity outside China carries a very different risk profile from a new mine.
What Investors Should Monitor
Most of the noise in this sector comes from tracking announcements without tracking their legal status. Five sources are worth more than the rest of the coverage combined.
- Draft legislation and consultations. A consultation document is the earliest signal available and costs nothing to read.
- Final regulations and official announcements. The ministry’s numbered announcement is the document that actually changes the legal position, so work from that text rather than from coverage of it.
- Permit and licence databases. Who is receiving approvals, and how long approvals take, tells you whether the system is open in practice.
- Customs guidance and tariff codes. Code-level detail is where scope quietly widens, and it is rarely covered by news outlets.
- Trade flow and inventory data. Export volumes, port activity and producer inventory confirm whether a policy changed physical supply.
Beyond those, three secondary feeds carry useful information: producer disclosures that describe permitted volumes, alternative project timelines outside the restricting jurisdiction, and the annual revisions to the official critical minerals lists themselves.
Separating a headline from a durable change comes down to four questions. Is the measure a ban, a quota or a licence? What share of global supply does it actually touch? What substitutes exist and how long do they take to qualify? And has any material volume moved yet? An announcement that fails the second and fourth questions is noise with a ticker attached.
How to Assess Whether a Restriction Will Matter
This framework takes about ten minutes per policy announcement.
- Name the exact mineral and stage. Rare earth concentrate and a sintered magnet are different products under different codes, and controls rarely cover both.
- Confirm the legal scope and effective date. Ban, quota or licence? Applies to everyone or to named destinations? Start date and duration?
- Measure the exposed supply. What share of global exports and of refining capacity falls inside the scope? If the number is small, so is the market impact.
- Check substitutes and alternative producers. Another producing country that can scale within a year changes the calculation more than any announcement text.
- Compare against inventories. Buyer stockpiles, producer inventory and strategic reserves buy months, and months is usually enough time for a substitution to work.
A worked example shows how the same policy produces different outcomes. Suppose a licence requirement is imposed on a processed material used in battery anodes, while a neighbouring stage remains open. The immediate effect is a licensing delay and a working capital cost for importers, because they must apply earlier and hold material longer before shipping. Prices move modestly if applications are granted on a normal timeline.
Now change one variable: the licence requirement becomes a ban on that stage. Importers cannot apply at all, so substitution accelerates immediately, alternative suppliers gain pricing power, and the price response is larger and longer lasting. The mineral is identical. The processing stage and the instrument are not, and that is where nearly all of the analytical work sits.
Frequently Asked Questions
No. Most measures are a quota, a case-by-case licence, an export tax, a domestic processing requirement or an end-use review. Only some are outright bans. For investors the distinction is decisive: a licence regime converts policy into a queue, and queues can clear quickly or stall entirely. Always check which instrument is in force before reacting to a headline.
Yes, and it happens more often than most readers expect. A state can require domestic refining of imported raw material, or it can extend licensing to foreign-made goods containing a controlled amount of domestic-origin content. China has used a value-based threshold of this kind for goods manufactured elsewhere. The restriction applies to the processing stage, not to who mined the material.
Because policy is only one input into delivered price. Buyers may hold inventory, the restriction may apply to a small share of global supply or only to specific destinations, and approvals may continue to flow under a licensing regime. Freight and substitution costs also land with a delay of weeks or months. Sharp headline moves often retrace once traders see actual licence approvals flowing.
Look for four confirmations: a final regulation rather than a consultation, licence data showing approvals granted or refused, a measurable gap between export volumes and prior levels, and qualified substitute material appearing in buyer designs. A policy that changes none of these is a headline. A policy that changes all four resets project economics and is worth repricing around.
No. Critical status describes supply risk, not policy. Official lists identify minerals with concentrated supply chains, import dependence or weak substitutes. Many listed minerals trade freely. Conversely, some controlled materials sit on watch lists without any active restriction. Read the list and the trade rules as two separate documents, because they are maintained for different purposes.
Conclusion
Export restrictions on critical minerals are a family of instruments, not a single rule, and they act at the level of a processing stage rather than a mineral name. The practical starting point for any reader is narrow: identify the exact material and stage, confirm the legal instrument and effective date from the official announcement, and check whether the measure is a ban or a licence.
From there, the market read follows fairly directly. Measure the exposed supply against inventories and substitutes, and check whether any material volume has moved yet. Only after those steps does an investment conclusion earn its place. Policies in this area change within weeks, so verify current official notices rather than relying on any summary, including this one.
Source: https://www.pgm-blog.com/what-are-export-restrictions-on-critical-minerals/
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,834,037,191 |
| Stories: | 8,715,887 |
Whistler Blowers, Insiders

